

PayPal POS (ex Zettle)
by PayPal Mobile
3.7
- Safety
- 100% Safe
- Category
- Business
- Ratings
- 3.7
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
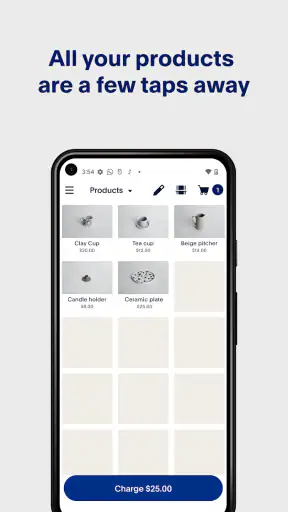
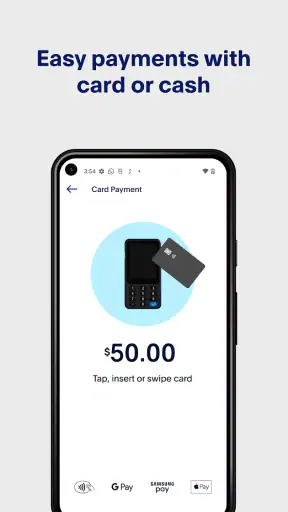
 Analysis by Getfullapps
When a household needs to accept payments at a stall, club activity, side business, or occasional sale, a phone-based point-of-sale tool can be more practical than keeping a separate terminal around. I tested PayPal POS with that shared-use situation in mind, rather than treating it like a personal finance app. My main impression is that it works best when one responsible person owns the payment account and other household members help with the physical selling, customer queue, or stock.
This is a free business app from PayPal Mobile, aimed at turning a compatible mobile setup into a point-of-sale workspace. Its average rating sits at 3.7 from around 43 thousand ratings, and it has passed the one-million-install mark. Those figures suggest a product with a real user base, but also one that will not feel perfect for everyone. I found the most important question is not simply whether it can help you take payments, but whether your household can agree on who controls the account, who handles the device, and who checks the results afterward.
Using one payment workspace between people
A realistic example would be a family selling handmade items at a weekend event. One person may manage the PayPal account, another may greet customers and select products, while a teenager helps keep the queue moving. In that arrangement, the app can serve as a shared sales screen without requiring every helper to become the account owner. That division is useful because payment responsibility and customer-facing work are not always the same job.
I would still avoid treating the app like a casual household utility that anyone can open and explore. A point-of-sale application sits close to money, customer information, transaction records, and business decisions. Even when the device belongs to the family, the payment workspace should have a clear owner. The person responsible for the account should prepare the products, review the totals, and decide who is allowed to operate the device during a sale.
This is where the app differs from a simple payment link or a personal wallet. A wallet is usually centered on an individual sending or receiving money. A POS tool is about organizing a selling process: choosing what is being sold, recording the transaction, and keeping the activity tied to a business or side venture. That makes it more useful for repeated sales, but it also creates more responsibility than casually accepting a transfer.
The strongest household setup is one account owner, one prepared device, and clearly assigned helpers. I would not pass the phone around without a plan, especially during a busy sale. A rushed handoff can lead to duplicate entries, confusion about whether a payment was completed, or accidental changes to the selling setup. The app can support coordination, but it cannot decide your family’s boundaries for you.
What the first setup should settle
Before using the app in front of customers, I would prepare it while the household is calm. Confirm which PayPal account belongs to the business activity, identify the device that will normally run the sale, and agree on who is permitted to change products or settings. This preparation is more important than it sounds because a shared device often contains personal apps, messages, photos, and other accounts that have nothing to do with the sale.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Keeping the POS session separate from ordinary phone use is a sensible habit. If several people use the same phone, the operator should know exactly which screen confirms a completed transaction and which screen is only an order or product step. I would also make sure the person supervising the sale understands how to recognize a finished payment before handing over an item. That is a practical safeguard, not a feature claim.
The app is listed for devices running Android 8.1 or later, so an older household phone may not be suitable. That minimum requirement matters when a family wants to reuse a spare device. A phone that still works well for calls or messaging may not be a good candidate if it cannot run the current app version, which is 8.31.2. Checking compatibility before preparing inventory avoids an unpleasant surprise at the counter.
Because the app is free, the initial decision is easier for a small household project. Free installation does not remove the need to think about payment processing, hardware compatibility, or the account arrangement used for the business. I would treat the app cost and the complete cost of operating a payment station as separate questions. That distinction helps prevent a family from assuming that downloading the app is the same as having every part of a POS system ready.
Sharing tasks without sharing everything
In my preferred workflow, the account owner prepares the catalog and checks the payment destination. A trusted helper then handles the customer-facing steps on the day. Another person can watch stock, wrap purchases, or keep a handwritten backup of items sold. This arrangement reduces the temptation to give every helper unrestricted control of the phone.
That boundary is particularly useful when a younger family member wants to participate. A teenager may be perfectly capable of selecting an item and following a checkout routine, while still not being the right person to manage account changes or reconcile money. I would explain the exact task rather than simply saying, “Use the app.” For example, the helper can select the correct item and pause for the responsible adult to confirm the payment before the product leaves the table.
For a small sale, this may feel slower than letting one person do everything. In practice, the extra pause can prevent a bigger problem. When several people are talking, customers are waiting, and the device is moving between hands, a clear verbal routine is valuable. The app records the sale, but the household still needs a shared method for confirming who has done what.
One non-obvious advantage of using a dedicated POS app instead of a general payment conversation is that it gives the sale a defined workspace. Helpers can focus on the sale rather than searching through personal messages or a banking application. The trade-off is that the workspace becomes more sensitive: the account owner should not confuse convenience with permission to give everyone the same access.
Age, trust, and the person holding the phone
The app carries an Everyone content rating, but that should not be mistaken for a recommendation that every child operate a payment account. The age label describes the app’s content context; it does not replace adult judgment about financial responsibility. In a household, I would separate “old enough to help at the table” from “trusted to control the account.” Those are different decisions.
A younger helper can have a useful role without handling sensitive account tasks. They might arrange products, read out the order, place a sticker on a package, or tell the adult which item the customer selected. An older and trusted helper may operate the checkout screen, but I would still establish a simple rule: no changes to account details, products, or money-related settings without the owner present.
This approach also protects the helper. If a customer disputes a transaction later, the responsible adult should know who was operating the device and what happened. A child or casual helper should not be left to explain a financial record alone. The app can be part of a supervised workflow, but it is not a substitute for supervision, family rules, or a clear business owner.
Trust matters between adults as well. A couple running a side business may share the work, but they should still agree on who reviews activity and how they handle refunds, corrections, or end-of-day totals. A shared phone does not automatically create shared understanding. I found that the most reliable use comes from deciding responsibilities before the first customer arrives, not from trying to reconstruct them afterward.
Where it fits beside familiar alternatives
Compared with cash, PayPal POS offers a more organized digital route for a seller who wants transactions associated with a point-of-sale process. Cash is familiar and does not depend on a phone screen at the moment of handover, but it requires change, physical storage, and later counting. The app is more convenient for a cash-light event, while cash remains a useful fallback when a device, connection, or customer preference makes digital payment impractical.
Compared with a bank transfer or a personal PayPal exchange, a POS-oriented workflow is better suited to selling several items rather than asking customers to send money manually. A personal transfer can be quick for a one-off arrangement, but it may leave the seller doing more work to identify what was purchased and reconcile the sale. The POS approach makes more sense when the same products are sold repeatedly and another person may need to help serve customers.
Compared with a dedicated card terminal, a phone-based app can be easier for a small operation that does not want another device on the table. The dedicated terminal alternative may feel more professional or more focused during a busy event, especially when the phone is also needed for calls, navigation, or inventory notes. I would choose the app for flexibility and occasional selling, and look harder at dedicated equipment when payment volume and speed become the main concern.
Compared with a full retail system, this app is likely to feel more approachable for a modest seller, but a larger household business may eventually want deeper staff management, detailed inventory control, or more formal reporting. I would not choose a lightweight mobile POS simply because it is free if the business already has multiple operators, complex stock, or strict accounting needs. The right comparison is not “which app has more buttons,” but “how much control and record keeping does this operation actually require?”
A practical day at a shared sale
Imagine a family table at a community event. Before opening, the account owner checks the phone, confirms the selling setup, and explains the handoff routine. One helper greets customers and selects items. The operator records the sale. A second helper wraps the purchase and marks the physical stock. If a customer asks for something unusual, the operator pauses and calls the owner rather than improvising.
That workflow uses the app where it is most valuable: as the central point for recording sales while people divide the surrounding work. It also limits the number of people who need to touch the payment screen. At the end, the owner reviews the recorded activity and compares it with the stock or notes. Even a basic manual cross-check can reveal whether an item was handed over before payment was confirmed or whether a sale was accidentally entered twice.
My tip is to create a short spoken confirmation that everyone uses. Something like “item selected,” “payment confirmed,” and “package handed over” sounds simple, but it prevents the common problem of three people assuming someone else completed the important step. The app cannot hear that conversation, yet the routine makes the app safer and easier to use in a crowded household setting.
I would also designate one person to troubleshoot. If the screen behaves unexpectedly or a customer asks about a transaction, helpers should know who makes the final decision. Having several people tap around at once is rarely helpful. A single operator, supported by observers, usually produces a cleaner record than a group trying to fix the same screen.
Small limitations that affect the decision
The biggest friction is the dependence on a shared device and a clear account boundary. If the only available phone is also the family’s main communication device, interruptions can make the selling process awkward. Calls, notifications, low battery, or a person needing the phone for another task can all compete with the POS role. A spare compatible device is more suitable, but that may not be available in every household.
There is also a learning curve that is easy to underestimate. The app may be straightforward once the workflow is familiar, but a helper arriving five minutes before a sale still needs an explanation. I would not rely on the store summary alone when training someone. Practice the sequence with a non-customer scenario, explain how the owner verifies the sale, and make sure everyone knows when to stop and ask for help.
The 3.7 average rating is a reminder to keep expectations realistic. It is not a reason to reject the app, but it does suggest that experiences vary. Device compatibility, account arrangements, payment situations, and the demands of different sellers can all affect satisfaction. I would test the complete setup before committing to an important event rather than assuming that a popular download will behave perfectly in every household.
Another limitation is conceptual: a POS application does not automatically solve family bookkeeping. Someone still needs to review what was sold, how the money should be divided, and which costs belong to the activity. If relatives are sharing a side business, write down those agreements separately. The app can support the transaction workflow, but it should not be treated as the household’s entire financial system.
Who should use it and who should look elsewhere
I think PayPal POS is a good fit for a small seller who already works within the PayPal ecosystem and wants a mobile point-of-sale option for occasional or growing sales. It is especially practical when one trusted adult can own the account while other household members help with customers, packaging, or product selection. The free price also makes it easier to explore without committing to a paid app before the workflow has proved useful.
I would be more cautious if several people need independent access, if the business requires detailed permissions, or if the phone must serve many unrelated purposes during the sale. A dedicated terminal or a more advanced retail platform may be better when speed, staff separation, and formal reporting matter more than portability. Likewise, a simple cash box may be less complicated for a very occasional sale with only a few transactions.
For families, the key question is whether they can maintain a clean boundary between participation and control. If the answer is yes, the app can give a shared selling activity a clear center without forcing everyone to manage the account. If the answer is no, the convenience of a phone-based POS may create more confusion than it removes.
PayPal Mobile has positioned this app in the business category rather than as a general household payment tool, and that distinction matches my experience. It is useful when the household is helping a business, not when everyone simply wants equal access to a personal payment account. The Everyone age rating makes the app broadly approachable, but responsible use still depends on the adult who owns the financial relationship.
My household verdict
After looking at it through a shared-device lens, I see PayPal POS as a sensible tool for a carefully organized household sale. I like the way it can give the payment side of a small operation a dedicated place while allowing family members to divide the surrounding tasks. I also appreciate that the app is free to install and available for a broad range of Android devices, including those running Android 8.1 or later.
My recommendation comes with a firm condition: keep one accountable owner, train helpers before the event, and do not confuse an Everyone content rating with unrestricted financial responsibility for children. Prepare the device, agree on who can change the setup, and use a simple confirmation routine during each sale. Those habits will matter as much as the app itself.
For a small family business or occasional seller, it is worth trying; for a busy operation needing complex staff controls, I would compare it with a dedicated terminal or fuller retail system. The app is at its best when it remains the focused payment workspace in a coordinated household workflow. It is less convincing when several people need equal control or when the family expects the app alone to manage every part of the business.
Pros
- Quick card and contactless payments with a compact mobile card reader.
- Supports multiple payment methods, including digital wallets and major cards.
- Sales, refunds, and receipts can be managed directly from the mobile app.
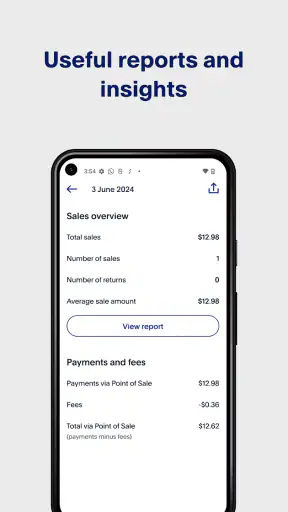
- Useful sales reports help track revenue, products, and transaction activity.
- No long-term contract makes it practical for seasonal or occasional businesses.
Cons
- Transaction fees can become costly for businesses with high sales volumes.
- Some advanced features require compatible hardware or additional accessories.
- Payment processing depends on a stable internet or mobile data connection.
- Availability of features and fees varies by country and business location.
- Customer support response times may be slower during busy periods.
FAQs for PayPal POS (ex Zettle)
What is PayPal POS, formerly known as Zettle, and who is it designed for?
PayPal POS is a point-of-sale solution for small businesses, independent sellers, market traders, cafés, service providers, and other merchants who need to accept payments in person. Formerly branded as Zettle in many markets, it combines the PayPal POS app with compatible card readers and optional accessories. It is especially useful for businesses that want a portable checkout rather than a complex traditional till system.
Which payment methods can I accept with PayPal POS?
Depending on your country, account type, and supported hardware, PayPal POS can accept major debit and credit cards, contactless payments, and mobile wallets such as Apple Pay or Google Pay. Customers can usually tap, insert, or swipe a card when the appropriate reader is connected. Payment availability and supported card networks vary by region, so checking the official PayPal information for your location before purchasing hardware is important.
Does PayPal POS require a card reader, and what equipment is compatible?
The app can be used for managing products, orders, and sales, but accepting in-person card payments generally requires a compatible PayPal POS card reader. PayPal offers different reader options depending on the market, including devices that support contactless and chip-and-PIN transactions. Some businesses also use receipt printers, cash drawers, barcode scanners, or stands, although these accessories may be optional and compatibility can differ between Android and iOS devices.
How much does PayPal POS cost, and are there transaction fees?
Downloading the PayPal POS app is typically free, but using the service involves payment-processing fees, and the exact rates depend on your country, transaction type, and PayPal merchant agreement. You may also need to pay separately for a card reader or other accessories. Before signing up, review the current pricing carefully, including in-person card fees, refunds, chargebacks, payout timing, and any applicable taxes or account requirements.
Can PayPal POS manage inventory, receipts, refunds, and business reports?
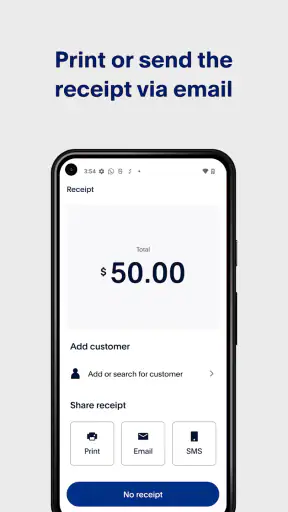
PayPal POS provides more than basic card acceptance. Depending on the version available in your region, you can create a product catalog, track stock, apply discounts, issue digital or printed receipts, process refunds, and review sales activity through the app. These tools are convenient for day-to-day operations, but businesses with advanced accounting, multi-location inventory, employee permissions, or detailed reporting should confirm whether the available features meet their specific requirements.

PayPal POS (ex Zettle)
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via hello@zettle.com, visit https://www.zettle.com, or review their https://www.izettle.com/gb/privacy-policy.










